Ghana Susu Savings & Loan Calculator
Calculate your Susu collector payout, ROSCA/group pot and rotation schedule, or Susu loan repayment — plus a comparison against interest-bearing savings.
31 working days is the traditional cycle length.
Effective fee: 3.23% of total contributions.
Illustrative planning estimates based on commonly cited Ghanaian Susu norms (31-day collector cycles, ~1-day/3.2% fee, flat or reducing-balance loan structures) — not a quote from any specific collector, group, or lender. Real Susu arrangements rely on trust and community norms and vary by group and provider. For a formal Susu loan, confirm exact rates with a licensed credit union, microfinance institution, or Susu company. Not financial advice.
How Susu Actually Works: A Practical Guide to Ghana’s Traditional Savings System
Last updated: August 2026·Reviewed by Kwame Asante, Tax Analyst in Accra·Source
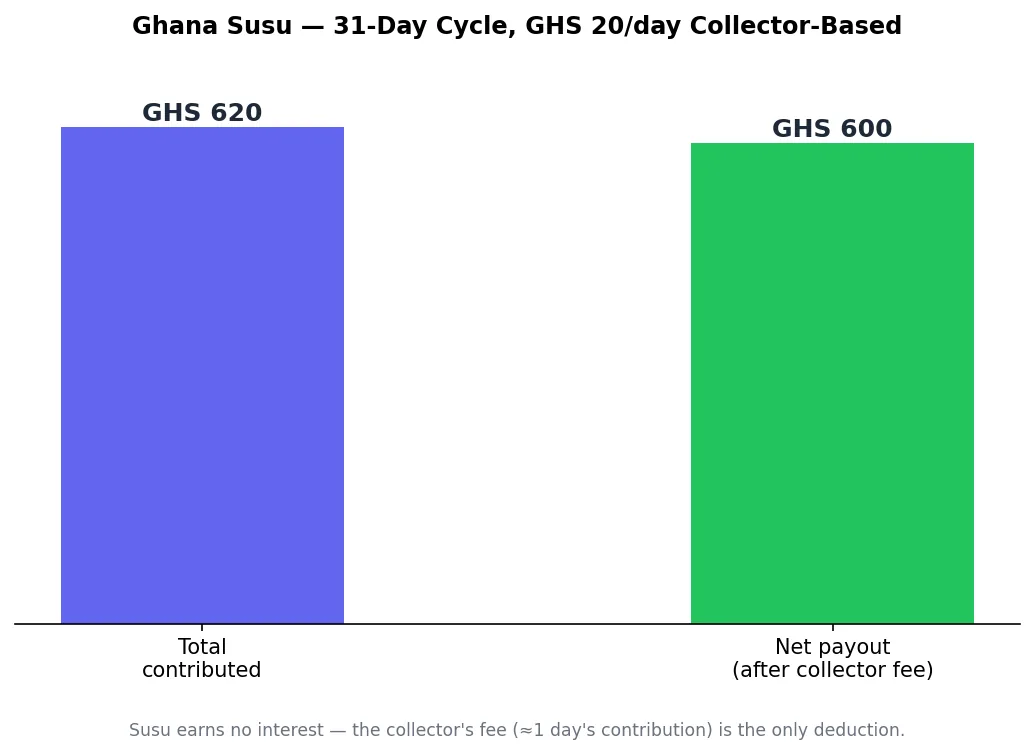
Susu earns no interest by design — the entire value is the discipline of saving daily amounts you'd otherwise spend.
The three common forms
| Type | How it works | What you get |
|---|---|---|
| Collector-based | Daily/regular contribution collected in person | Total back, minus ~1 day's contribution as fee |
| Rotating (ROSCA) | Fixed group contribution, one member paid per round | An interest-free advance (early) or your own savings back (late) |
| Susu-linked loan | Borrow against your balance, up to 2–3× | Flat-rate or reducing-balance interest |
Worked example
A trader contributes GHS 20/day to a collector over a 31-day cycle.
- Total contributed: GHS 20 × 31 = GHS 620
- Collector's fee (1 day's contribution, ≈3.2%): GHS 20
- Net payout: GHS 600
Things to know
- Rotating Susu position matters: receiving the pot early gives you an interest-free advance on contributions you haven't made yet; receiving it late means you've effectively funded everyone ahead of you.
- Susu-linked loans quoted as a flat rate versus a monthly reducing-balance rate can produce noticeably different total costs for the same headline percentage — always run both.
- Traditional collectors and informal groups have historically operated with light-touch oversight; a formally registered Susu company or credit union under Bank of Ghana's framework carries different risk from an informal collector.
Long before mobile money or formal banking reached every corner of Ghana, Susu was already doing the job of getting ordinary people into the habit of saving, and it still does that job today, often better than more "modern" alternatives manage to. If you've never used it, or you're trying to work out exactly how much you'll walk away with at the end of a cycle, the mechanics are worth understanding properly rather than guessing.
The most familiar version is collector-based Susu: you agree a fixed amount with a Susu collector — traditionally called a Susu man or Susu woman — and they visit you daily (or on whatever schedule you agree) to collect that amount. At the end of a cycle, conventionally 31 working days, they return your total contributions minus a fee, commonly cited as the equivalent of one day's contribution, which works out to roughly 3.2% of the cycle total. You earn no interest under this model — the entire value proposition is discipline, not growth. For someone who knows they'll spend money sitting idle in their pocket or mobile wallet but won't touch cash that's already "gone" to the collector, that discipline is genuinely worth paying a small fee for, even though the maths on paper looks like a guaranteed loss compared to a savings account.
The second common form is rotating Susu, more formally a ROSCA (Rotating Savings and Credit Association) — a group of people who each contribute a fixed amount every round, with one member receiving the entire pot on a rotating basis until everyone has had a turn. If you're early in the rotation order, you effectively receive an interest-free advance on contributions you haven't made yet, which is genuinely valuable if you need a lump sum sooner rather than later. If you're later in the rotation, you're essentially the one funding those early advances, receiving your own money back after having patiently paid into the pot for months. Neither position is objectively "better" — it depends entirely on whether you need the lump sum now or are comfortable building toward it — but it's worth entering a rotation with your eyes open about which position you've been given and what that means for your own cash flow.
A third, more formal option has grown alongside the traditional system: Susu-linked loans, offered by some credit unions and microfinance institutions built around the Susu concept, letting you borrow against your accumulated savings, often up to two or three times your balance. These loans are typically quoted either as a flat rate — a fixed percentage of the principal charged once and spread evenly over the term — or as a monthly reducing-balance rate, where interest is calculated each month on whatever balance remains outstanding. The two structures can produce noticeably different total costs for what looks like a similar headline percentage, which is exactly why it's worth running both through a calculator rather than comparing the quoted rates at face value.
It's worth being upfront about how Susu sits within Ghana's regulatory landscape too, since it affects how much protection you should expect. Traditional Susu collectors and informal rotating groups have historically operated with light-touch oversight, relying on community trust and reputation rather than a formal contract or deposit guarantee. Bank of Ghana has been moving parts of this space into a more formal "Last-Mile Providers" category as part of a broader microfinance and cooperative framework, but that transition doesn't cover every informal collector or every neighbourhood rotating group. In practice, this means the safety of your Susu arrangement still depends heavily on who you're dealing with — a well-established, formally registered Susu company or credit union carries materially different risk from an informal collector you've only recently started working with, and it's worth treating that difference seriously before committing meaningful sums.
None of this is a reason to avoid Susu — for millions of Ghanaians, especially traders, artisans, and anyone paid in irregular daily amounts rather than a fixed monthly salary, it remains one of the most effective savings tools available precisely because it matches how their income actually arrives. But going in with a clear, calculated sense of your net payout, your position in a rotation, or the real cost of a Susu-linked loan — rather than a rough verbal estimate — makes it a tool you're using deliberately, not one you're simply trusting blindly.